Does Homeowners Insurance Cover Foundation Repair in Georgia?
Need help with your own home?
Tell us your concern. We'll check local contractor availability.
No referral fee · No obligation to hire
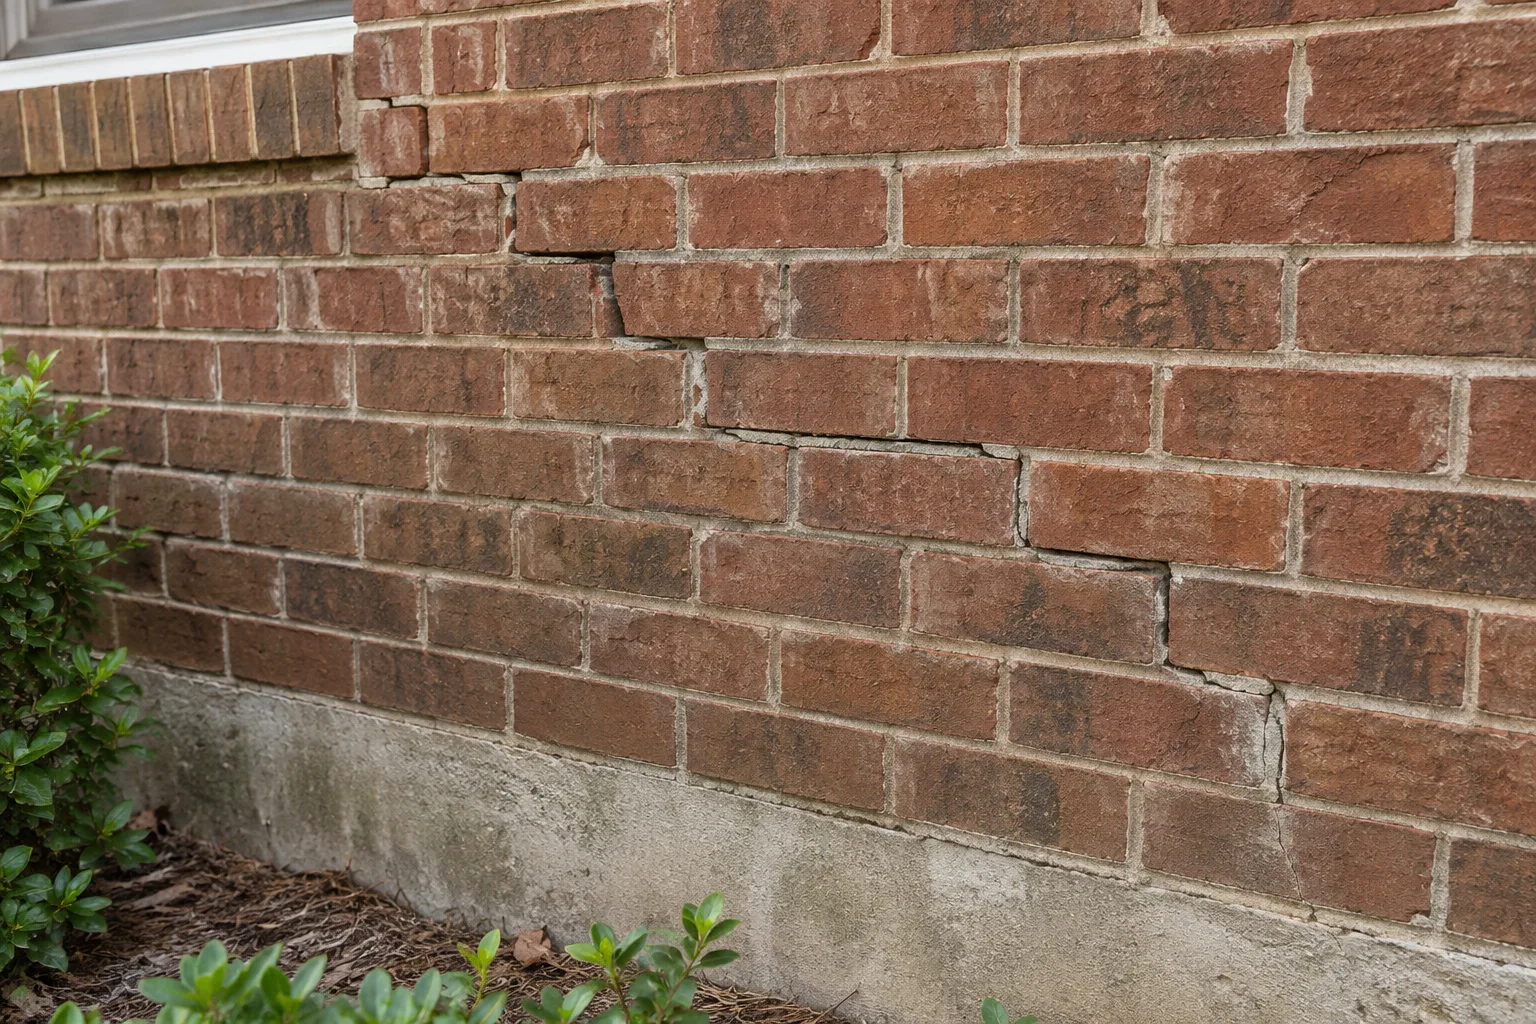
Does homeowners insurance cover foundation repair in Georgia?
There is no universal yes-or-no answer for foundation damage. Coverage depends on the policy wording, endorsements, exclusions, deductible, documented cause, and claim facts. Gradual settlement, soil movement, wear, drainage, a plumbing event, or another cause may be treated differently under a particular policy; confirm the actual terms with your carrier or agent.
A policy may address sudden events, gradual conditions, water, earth movement, wear, or maintenance in different ways. Do not assume that a general Georgia rule, local soil story, or visible crack predicts coverage. Ask the carrier what provisions and evidence apply to the documented loss.
Insurance decisions turn on the policy language and documented cause. Gradual settlement, soil movement, drainage, and wear may be excluded, while a sudden covered event may be treated differently. Ask your carrier or agent before relying on a claim outcome.
Marietta Foundation Repair is a referral service, not a contractor or an insurance company. We do not perform repairs, file claims or provide insurance advice. An introduction may be requested but is not guaranteed. Confirm contractor credentials and assessment terms directly, and ask your insurer about your actual policy. For planning questions, see the foundation repair cost estimator.
How can a policy address different foundation-damage causes?
A policy may contain settling, earth-movement, wear or water-related exclusions, but coverage depends on its wording, endorsements and the facts. Review your policy and ask the insurer how it applies; this guide does not establish the most common local cause or claim outcome.
Foundation claims depend on the policy, endorsements, exclusions and facts of the loss. Do not assume that a local soil explanation or a general list of exclusions predicts your insurer's decision.
Document observations and relevant events, review your policy and ask your insurer for its coverage position. A sudden event is not automatically covered, and a gradual condition cannot be evaluated from this guide alone.
- Ask how the policy treats settling and differential movement.
- Review the actual earth-movement language and any endorsements.
- Ask whether wear, deterioration or maintenance exclusions apply to the documented loss.
- Document water paths without assuming how drainage affects coverage.
- Do not infer a tree-related cause or exclusion from proximity alone.
- Check whether flood or earthquake coverage requires separate protection.
When might homeowners insurance cover foundation repair?
A sudden event such as a plumbing failure, fire, impact, or another peril may be relevant to a claim only if the policy covers that event and the documented facts link it to the foundation damage. A gradual condition may be treated under different provisions. The insurer decides coverage under the actual policy; this guide cannot predict it.
Document the event and damage without assuming that a pipe failure, water discharge, fire, impact, or another event is covered. Ask the carrier which policy provision, deductible, exclusions, causation evidence, and mitigation steps apply.
Other events may be relevant depending on the policy and facts, but no list establishes coverage. Preserve records, report promptly as required by the policy, and ask the insurer or an appropriately qualified adviser about the claim.
The point of this section is to identify questions, not to predict payment. Two similar-looking losses can be treated differently under different policies or documented causes. Do not authorize work or rely on a coverage assumption without confirming the insurer's position.
How should I compare a sudden event with gradual foundation changes?
Cause and timing can matter, but a sudden event is not automatically covered and gradual damage cannot be evaluated from a general rule alone. Ask your insurer to explain applicable provisions and exclusions using the documented facts.
Cause, timing and policy language can affect a claim, but the distinction between a sudden event and a gradual process is not a coverage decision. Ask your insurer to explain applicable terms and exclusions.
If an assessment is offered, confirm its scope, fee and written findings. Ask the provider to separate observations from conclusions. We do not promise diagnostic documentation or predict whether it will support a claim.
The warning-sign guide and assessment guide can help organize questions. Coverage advice and claim decisions come from the relevant insurer or appropriately qualified adviser.
How do I document foundation damage for an insurance claim?
Document observations, dates, relevant events, photos, invoices, mitigation, and policy records. A contractor or other professional may document conditions and possible explanations, but the insurer evaluates cause and coverage under the policy. Do not require a provider to state a definitive cause that the evidence cannot establish.
Whether or not a claim succeeds, preserve a dated record before repairs alter the evidence. Photograph cracks and water conditions with a scale, save plumbing or other event records, and ask the insurer what notice, mitigation, inspection, and documentation it requires.
If you do file, read your declarations page and policy exclusions first so you understand your own coverage, deductible, and any time limits for reporting a loss. Georgia policies vary widely between carriers. Marietta Foundation Repair does not file claims or give insurance advice — talk to your agent and, for disputed or high-value claims, consider a licensed public adjuster or attorney.
- Photograph and date everything — wide shots and close-ups of every crack, with a coin or ruler for scale; re-photograph over time to show whether movement is sudden or gradual.
- Preserve evidence of the trigger — for a burst pipe, keep photos of the failed line, plumber invoices, and any water-mitigation records before repairs cover them up.
- Obtain written observations - ask an appropriate professional to document visible conditions, measurements, possible explanations, limitations, and recommended next questions; do not assume a report can establish coverage.
- Keep a paper trail — receipts, repair estimates, your policy declarations page, and dated notes of every call with your carrier or agent.
- Report promptly - review the policy's notice requirements and report a loss within the stated period; do not infer a deadline or outcome from this guide.
- Don't assume — confirm — review your policy language and call your carrier before counting on any reimbursement.
How can soil context affect foundation-claim questions?
Gradual settlement may fall under earth-movement or settling exclusions, but coverage depends on the policy and cause. Mapped soil information is regional context, not proof of what happened at one home. Read the exclusions and ask the carrier how it would classify the documented event.
Ask whether any written findings distinguish observations, possible explanations and unresolved questions. A regional soil name does not establish the cause of a loss.
A symptom can become noticeable suddenly without establishing when its cause began. Neither a jammed door nor a crack pattern proves settlement or determines coverage.
See foundation-crack context for questions about drainage, fill, construction and other site factors. Discuss the actual policy and documented facts with your insurer.
How should I plan if coverage is uncertain?
If a claim is denied or excluded, ask the insurer to explain the decision and plan from a property-specific proposal, not a presumed repair. Published amounts here are illustrative budgets, not verified local prices or an exact quote. Assessment fees, proposed work, financing eligibility and payment terms require direct confirmation.
Coverage depends on the policy, cause and evidence; do not assume an insurer will approve or deny a particular foundation claim. If you will pay for repairs yourself, compare the proposed method, quantities, exclusions and change-order terms. The $3,500–$25,000+ figures elsewhere on this site are rough budgeting examples, not a verified Cobb County price distribution or an offer.
Published planning ranges vary by method and scope: crack repair, deep support, slab leveling, bowing-wall reinforcement, waterproofing, and encapsulation each depend on measurements, access, quantities, and materials. These figures are rough budgeting context, not verified Cobb County price data or a contractor quote.
Published planning ranges vary by method and scope and are not verified local prices or quotes. Ask any contractor or lender for the actual written scope, eligibility, APR, fees, total repayment, and change terms; do not infer that financing is available.
What should a Georgia homeowner do next?
Read the policy and ask the carrier how it applies to the documented facts. Preserve evidence of any relevant event, request the insurer's instructions in writing, and obtain property-specific repair information separately. This referral service is not an insurer or contractor; any assessment, scope, and price require direct confirmation.
Start with the declarations page, policy provisions, endorsements, and claim-reporting instructions, then ask the carrier or agent what information it needs. Document damage and relevant events before repairs change the evidence. Coverage cannot be inferred from a regional soil label or symptom.
That last step is where a referral may help with logistics, not diagnosis. Marietta Foundation Repair is a disclosed lead-referral service serving Marietta, East Cobb, Smyrna, Kennesaw, Acworth, and Powder Springs. We may check whether a suitable contractor is available; verify credentials, scope, fees, and any written diagnosis directly. The referral request has no fee from this service, and we do not perform the work or give insurance advice.
Review the warning signs, use the cost guide only for planning, and prepare questions with the assessment guide. Any introduction, assessment, diagnosis or quote requires direct confirmation. This is educational information, not insurance, legal or financial advice; confirm coverage with your insurer.
Frequently asked questions
Does homeowners insurance cover foundation repair in Georgia?
There is no universal answer. Policy wording, endorsements, exclusions, deductible, documented cause, and claim facts control. Ask your insurer or agent how the actual loss is treated rather than relying on a general rule about settlement, soil movement, wear, water, or sudden events.
Will my policy pay if Georgia red clay caused my foundation to settle?
Do not assume a regional soil label decides the claim. Ask the insurer how it classifies the documented cause, review earth-movement and settling exclusions, and preserve evidence of any sudden event such as a burst pipe.
My foundation was damaged by a burst pipe — is that covered?
It may be relevant, but a burst pipe does not by itself establish coverage or causation. Preserve evidence, report the loss according to the policy, and ask the carrier how the event, resulting damage, exclusions, deductible, and required documentation apply.
How do I document foundation damage for an insurance claim?
Photograph and date cracks and water conditions with a scale, preserve records of any relevant event and mitigation, keep receipts and policy documents, and report promptly as required. Ask the carrier what inspections or records it requires; a professional may document observations without being able to decide coverage.
Does Marietta Foundation Repair file insurance claims or give insurance advice?
No. Marietta Foundation Repair is a disclosed lead-referral service, not an insurer or contractor. We do not perform repairs, file insurance claims, or provide insurance, legal, or financial advice. For coverage questions, talk to your own carrier or agent; confirm any contractor terms directly.
If insurance won't pay, how much should I budget for foundation repair?
Start with the insurer's written coverage decision and a contractor's proposed scope. Our published ranges are rough planning examples, not verified local prices. Confirm assessment fees, whether a written proposal is offered, and any financing APR, fees and eligibility directly. This service does not provide financing or guarantee a quote.